 By
Let me be upfront about something before we start: I am not one of those people who thinks giving up your morning coffee will make you rich. The ‘latte factor’ as a concept is both mathematically real and wildly overblown as a financial strategy. Skipping a $5 coffee every day saves you $1,825 a year. That’s real money. But it’s also not the reason most people are financially struggling, and treating it as the primary lever of financial improvement is insulting to the actual complexity of most people’s money situations.
That said — I did actually stop buying coffee from cafes for three months. Not because I read a finance article telling me to, but because I was genuinely curious what would happen if I tracked it carefully. And the results were more interesting than I expected.
The Experiment: What I Actually Did
I spent an average of £4.20 per coffee, typically once or twice a day on workdays. Before I stopped, I calculated what that actually cost me annually: roughly £1,100 per year across 260 working days. I then invested about £180 in a decent espresso machine and good beans from a specialty roaster, and made coffee at home for three months while tracking everything.
What I saved over 90 days was approximately £320 net of the equipment cost — about £3.50 per day. Not transformative. But also not nothing. What I didn’t expect was what else changed.
The Hidden Costs I Hadn’t Counted
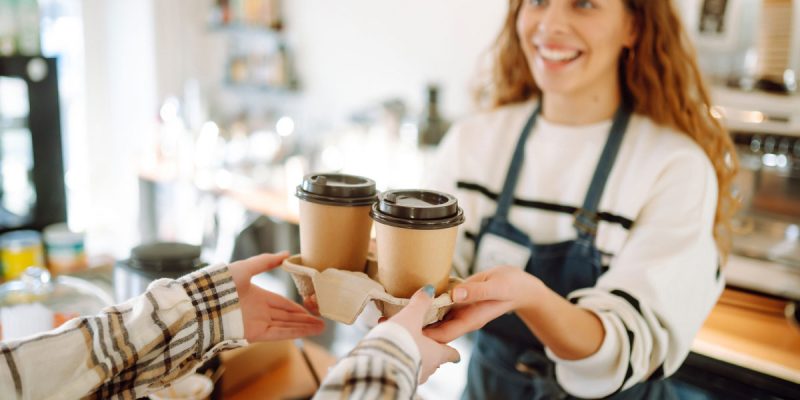
The coffee shop wasn’t just a coffee purchase. It was a food purchase (I almost always grabbed something to eat too), a workspace booking (I work from home and would go there to change environment), and occasionally a social purchase (meeting someone). When I stopped going, I noticed I was spending less on those ancillary things too. The total daily spend at a coffee shop, when I added everything honestly, was closer to £8-10 rather than £4.20. That changes the math significantly.
The Home Coffee Reality
Here’s what the personal finance content doesn’t usually tell you: making genuinely good coffee at home takes practice. My first two weeks of espresso were mediocre. By week six, I was making something I genuinely preferred to the chain coffee I’d been buying. The Sage Bambino I bought for £180 paid back its cost in under two months of the experiment. The quality of beans matters enormously — spending £10-12 per 250g bag of freshly roasted specialty beans is still a fraction of the per-cup cost of a coffee shop.
What the Money Actually Went To
I tracked where the saved money went, which is where the personal finance lesson really lives. Some of it went to other things automatically — groceries, online purchases, other small spending that expanded slightly to fill the space. This is lifestyle inflation in miniature: free money has a way of being absorbed unless you deliberately redirect it. I had to actively move the saved amount to savings each week to prevent this absorption. The automation lesson applies even to small daily savings: without a system, freed-up money drifts rather than compounds.
What I Missed (Honestly)
I missed the ritual more than the coffee. The walk to the coffee shop. The brief conversation with the barista. The change of environment. These things have real value that home coffee doesn’t replicate, which is why the decision to cut coffee spending entirely isn’t as simple as the financial math suggests. What I eventually settled on: making home coffee my default, but going to a coffee shop once or twice a week deliberately — as an experience rather than a habit. This cut my coffee spending by about 60% while preserving most of what I actually valued about it.
The Actual Financial Lesson
The real insight from this experiment wasn’t about coffee at all. It was about the difference between habitual spending and intentional spending. The £4.20 coffee bought out of habit — barely noticed, easily forgotten — versus the £4.20 coffee bought deliberately as a treat, enjoyed properly, remembered. The first is financial noise. The second is a genuine choice. Applying this distinction to all spending — not just coffee — is what actually changes your financial life. Coffee was just the easiest place to start seeing it.
Pros and Cons of Cutting Coffee Spending
Pros: Real savings of £100-150+ per month for daily cafe coffee drinkers. Forces development of home coffee skills that produce genuinely better results over time. Reveals the difference between habitual and intentional spending in a low-stakes context. Equipment investment pays back quickly and keeps paying indefinitely.
Cons: The coffee shop experience has genuine value (environment, social element, ritual) that home coffee doesn’t fully replace. Equipment produces mediocre results initially before skill develops. The savings, while real, are modest compared to larger financial levers like housing and transport costs. Cutting coffee while ignoring bigger spending categories is a form of financial procrastination dressed up as virtue.